Idaho Department of Insurance - What Injury Victims Need to Know
The Idaho Department of Insurance (IDI) regulates every insurance company doing business in Idaho, including the auto insurers, homeowners carriers, and commercial liability underwriters that pay out personal injury claims. For accident victims, understanding how this agency operates can mean the difference between a claim handled fairly and one buried under bad-faith delays. The IDI does not litigate your case for you, but its rules shape the playing field on which every Idaho personal injury claim unfolds.
What the Idaho Department of Insurance Actually Does
The IDI licenses insurers, reviews policy forms, enforces solvency requirements, and investigates consumer complaints. It operates under Title 41 of the Idaho Code, which grants it authority to sanction carriers that engage in unfair claims settlement practices. Those practices include failing to acknowledge a claim promptly, misrepresenting policy terms, and refusing to pay valid claims without reasonable investigation.
For injury victims, the most practical function of the IDI is its complaint process. Filing a complaint with the IDI against an insurer does not compel a settlement, but it creates a formal record of the insurer's conduct. That record can become relevant if your attorney later argues that the carrier acted in bad faith.
How Idaho's Insurance Rules Affect Personal Injury Claims
Idaho is a fault-based state, meaning the at-fault party's liability insurance is responsible for covering the injured person's losses. Idaho's minimum auto liability limits are $25,000 per person and $50,000 per accident for bodily injury, with $15,000 for property damage. Many drivers carry only these minimums, which frequently fall short of covering serious injuries.
Idaho's modified comparative fault rule adds another layer of complexity. A plaintiff who is found 51% or more at fault loses the right to recover entirely. At 50% or less, the plaintiff may still recover damages, but those damages are reduced in proportion to their share of fault. Insurers are well aware of this rule and will investigate every detail of an accident to assign as much fault to the claimant as possible.
Minimum Coverage and Underinsured Motorist Protection
Underinsured motorist (UIM) coverage is not required in Idaho, but insurers must offer it. If you were injured by a driver carrying only minimum limits and your medical bills exceed those limits, your own UIM coverage can bridge the gap. Review your declarations page carefully, because many Idahoans unknowingly waived UIM coverage when they signed their original policy.
Uninsured motorist coverage follows a similar structure. If the at-fault driver had no insurance at all, your own uninsured motorist policy is often the only source of compensation available. The IDI requires that any waiver of these coverages be documented in writing by the policyholder.
Filing a Complaint with the Idaho Department of Insurance
The IDI accepts complaints online, by mail, and by phone. To file effectively, gather your policy number, the claim number, any written correspondence with the adjuster, and a clear timeline of events. The IDI will contact the insurer and require a formal response, typically within 21 days.
Common grounds for complaint in personal injury contexts include unreasonable delays in claim acknowledgment, lowball settlement offers unsupported by evidence, and failure to communicate in writing. The IDI cannot award you damages, but a substantiated complaint can prompt the agency to issue a warning or fine, and it signals to the insurer that its conduct is being scrutinized.
What the IDI Cannot Do
The IDI is a regulatory body, not a civil court. It cannot force an insurer to pay a specific dollar amount, reverse a coverage denial on your behalf, or provide legal representation. If an insurer has denied your claim improperly or refuses to negotiate in good faith, the appropriate remedy is a civil lawsuit, not an IDI complaint alone.
That distinction matters because some claimants file an IDI complaint as a substitute for legal action, then miss the deadline to sue. Idaho's statute of limitations for general personal injury claims is 2 years from the date of injury under Idaho Code § 5-219. Missing that deadline typically bars recovery entirely, regardless of how strong your underlying claim may be.
How Insurers Use the Claims Process Against You
Insurance adjusters work for the carrier, not for you. Their job is to close claims at the lowest possible cost. Common tactics include requesting recorded statements early in the process, before you know the full extent of your injuries, and sending medical authorization forms that give them access to your entire medical history rather than just records related to the accident.
Consult an attorney before giving a recorded statement to any insurance adjuster. A statement made without legal guidance can be used to minimize your injury, shift fault onto you, or contradict your later account of events. The IDI's unfair claims settlement rules prohibit outright misrepresentation, but they do not prevent adjusters from using legally permissible tactics that still disadvantage claimants.
Documenting Your Claim for Maximum Effect
Keep a written log of every contact with the insurer: date, time, name of the representative, and what was said. Save all emails and letters. Photograph every stage of your recovery, including visible injuries, medical equipment, and any home modifications you needed. Economic damages in Idaho personal injury claims include medical expenses, lost wages, property damage, and future care costs.
Non-economic damages cover pain and suffering, emotional distress, and loss of enjoyment of life. Strong documentation supports every category.
Working with an Idaho Personal Injury Attorney
Most Idaho personal injury attorneys handle cases on a contingency fee agreement, meaning you owe no attorney's fees unless the case resolves in your favor. Standard contingency fees range from 33%–40% of the settlement or award. If the case proceeds to trial, that percentage typically rises to 40%–45% of the award. Initial consultations are free at most Idaho personal injury firms.
An attorney can communicate with adjusters on your behalf, preserve evidence before it disappears, and identify all available insurance policies, including umbrella policies and employer-carried coverage. Idaho personal injury cases that settle take an average of 6–18 months from the date of hiring an attorney. Cases that go through full litigation in Idaho's 7 judicial district courts typically take 2–4 years from the date of injury.
Government Entities and the Idaho Tort Claims Act
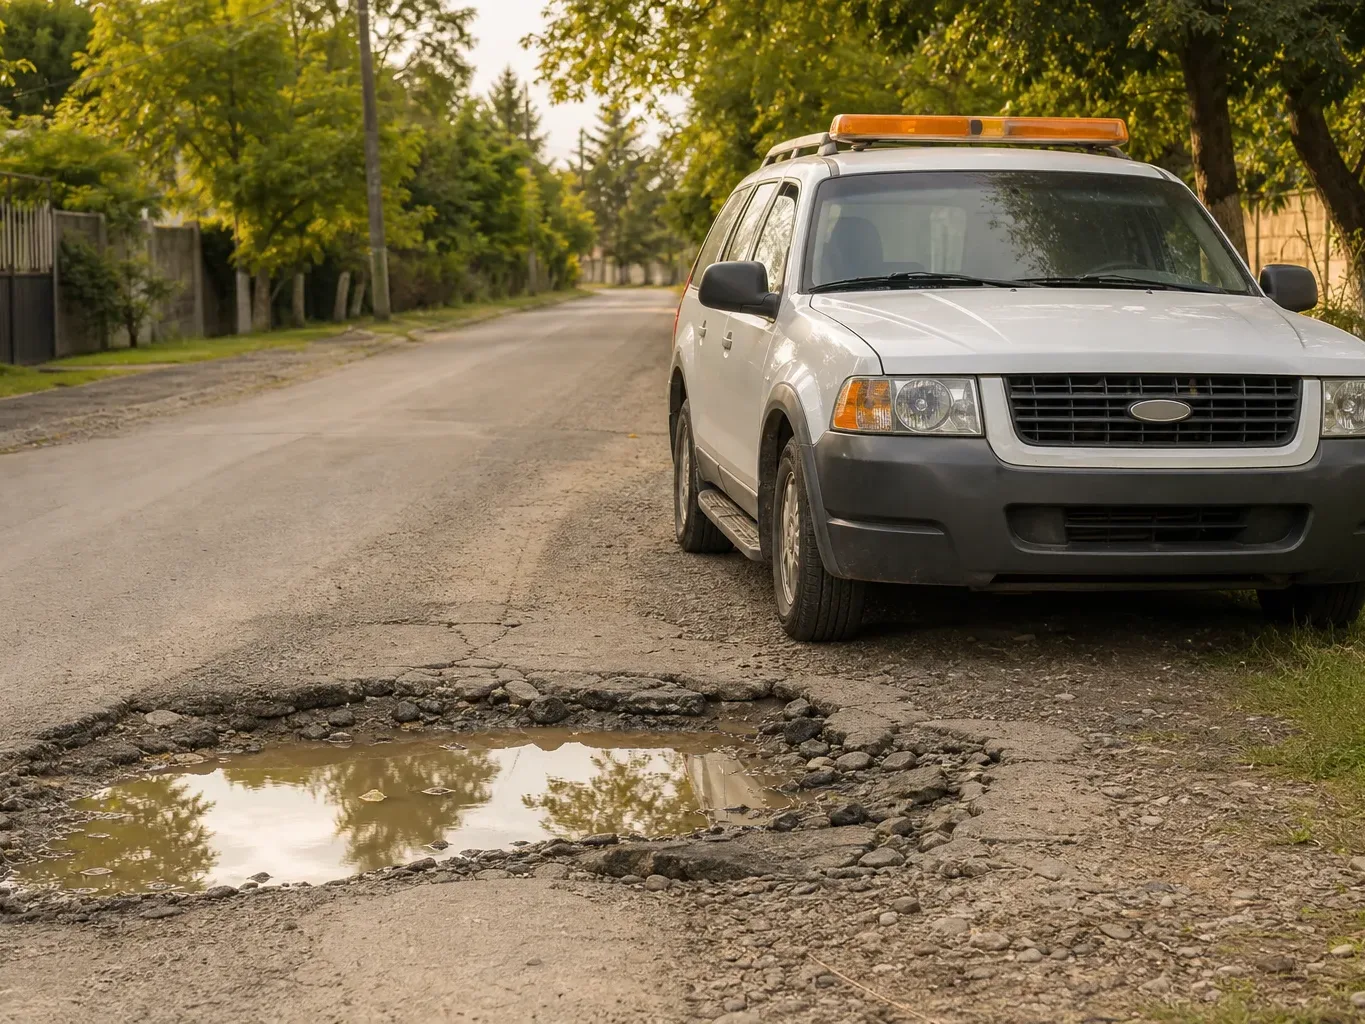
If your injury involved a government-owned vehicle, a defective road, or negligence by a state or local employee, different rules apply. The Idaho Tort Claims Act (ITCA) governs claims against state and local government entities. Under the ITCA, you must file a tort claim notice within 180 days of the injury before you can sue. After that notice, you have up to 2 years to file a lawsuit.
Missing the 180-day notice deadline is fatal to a government liability claim. The IDI does not handle ITCA notices. Those go directly to the relevant government entity, such as the Idaho Transportation Department for highway defect claims or the city clerk for municipal negligence. An attorney familiar with the ITCA can confirm the correct recipient and preserve your rights before the window closes.
Frequently Asked Questions
Can the Idaho Department of Insurance Force an Insurer to Pay My Personal Injury Claim?
No. The IDI is a regulatory agency that can investigate complaints and sanction insurers for unfair practices, but it cannot award damages or compel a specific settlement. If an insurer has wrongfully denied your claim, a civil lawsuit is the appropriate path to compensation.
How Long Do I Have to File a Personal Injury Lawsuit in Idaho?
Idaho Code § 5-219 gives you 2 years from the date of injury to file a personal injury lawsuit. Missing this deadline typically bars recovery entirely. If a government entity is involved, you must first file a tort claim notice within 180 days under the Idaho Tort Claims Act.
What Is Idaho's Modified Comparative Fault Rule and How Does It Affect My Claim?
Idaho follows a modified comparative fault rule. If you are found 51% or more at fault for your injury, you cannot recover any damages. At 50% or less at fault, you may still recover, but your damages are reduced by your percentage of fault. Insurers actively investigate accidents to assign as much fault to claimants as possible.
Should I Give a Recorded Statement to the Insurance Adjuster After an Accident?
Consult an attorney before giving a recorded statement to any insurance adjuster. Statements made early in the process, before you know the full scope of your injuries, can be used to minimize your claim or shift fault onto you. This guidance applies whether you are dealing with your own insurer or the at-fault driver's carrier.
How Much Does a Personal Injury Attorney in Idaho Cost?
Most Idaho personal injury attorneys work on a contingency fee agreement, so you pay nothing upfront. Standard fees range from 33%–40% of the settlement or award, rising to 40%–45% if the case goes to trial. Initial consultations are free at most Idaho personal injury firms.